UAE small business relief extended to 2029: what stays the same
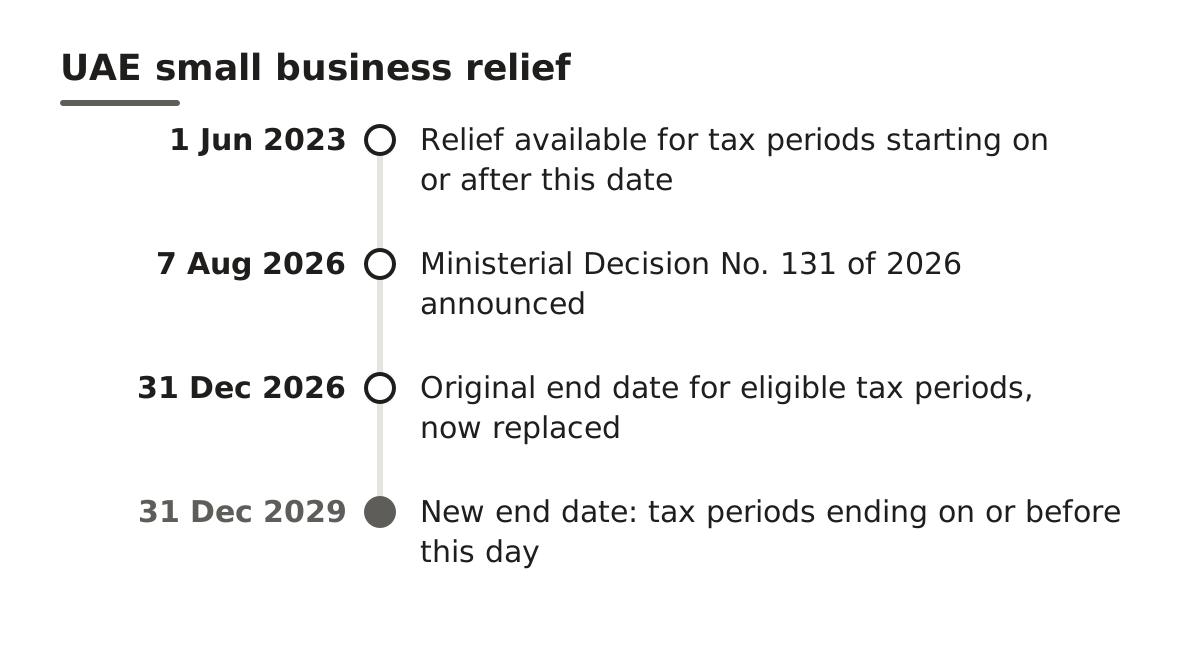
Small UAE businesses have three more years of relief from corporate tax. On 7 August 2026, the Ministry of Finance announced Ministerial Decision No. 131 of 2026, which extends small business relief to tax periods ending on or before 31 December 2029. Before this, the relief was due to stop with tax periods ending on 31 December 2026. The AED 3 million revenue limit, the exclusions and the way you claim it are all unchanged.
If you run a small company or trade as a freelancer in the UAE and your revenue stays at or under AED 3 million, this is good news with very little small print. The small print that does exist is worth reading, though, because one bad year can knock you out of the relief permanently.
What changed
Only the end date. Ministerial Decision No. 131 of 2026 amends Ministerial Decision No. 73 of 2023, which created the relief. The window now covers tax periods starting on or after 1 June 2023 and ending on or before 31 December 2029.
What stays the same
The Federal Tax Authority’s guidance sets out the conditions, and none of them has moved:
- Revenue of AED 3 million or less in the current tax period and in every previous tax period.
- Resident persons only, both companies and individuals.
- Two groups are excluded: Qualifying Free Zone Persons, and members of multinational groups with consolidated group revenue above AED 3.15 billion.
- You have to elect it for each tax period. It isn’t automatic.
- If you elect, you’re treated as having no taxable income for the period, and other exemptions, reliefs and deductions aren’t available.
- No transfer pricing documentation is needed, but dealings with related parties still have to be at arm’s length.
Who this affects
- Small mainland companies with revenue at or below AED 3 million, from consultancies to cafés.
- Freelancers and sole traders. A natural person doing business in the UAE falls within corporate tax only once turnover from business activities passes AED 1 million in a calendar year. Those between AED 1 million and AED 3 million can elect the relief.
- Foreign-owned small businesses resident in the UAE, provided they aren’t part of a multinational group above the AED 3.15 billion line.
- Free zone companies have a choice to make. A company that qualifies as a Qualifying Free Zone Person can’t use the relief, so it needs to compare the two regimes.
What it means in practice
Take Zayed Studio, a Dubai design consultancy with a December year end. Its revenue history looks like this:
| Tax year | Revenue | Relief available? |
|---|---|---|
| 2024 | AED 2.1 million | Yes, if elected |
| 2025 | AED 2.6 million | Yes, if elected |
| 2026 | AED 2.9 million | Yes, if elected |
| 2027 | AED 3.2 million | No, revenue is over AED 3 million |
| 2028 | AED 2.7 million | No, because 2027 was over the limit |
Without the extension, Zayed Studio would have lost the relief from 2027 anyway. With it, the studio could have claimed relief to the end of 2029, but its strong 2027 ends that. The FTA’s own example makes the same point: a business with AED 1.9 million of revenue this year is still out if a previous year was above AED 3 million.
Once outside the relief, the normal rates apply. The Ministry of Finance has confirmed the 0% band on taxable income up to AED 375,000, with 9% above that. If Zayed Studio’s 2027 taxable income is AED 900,000, the tax is 9% of AED 525,000, which is AED 47,250.
That’s why the planning question is timing. If a large contract would push revenue just over AED 3 million, it’s worth thinking about whether that’s the year you want to leave the relief for good. Don’t be tempted to split the business into two companies to stay under the limit, though. That’s exactly the kind of arrangement tax authorities look at hard, so take advice before any restructuring.
What to do now
- Check your revenue for every tax period since your first under corporate tax. One period above AED 3 million means you can’t elect again.
- Remember to make the election in each return. It’s easy to miss.
- Keep proper records and file on time even when you elect. The relief lightens the calculation, not the filing.
- Price related-party dealings at arm’s length, even though you don’t need formal transfer pricing files.
- If you’re a freelancer near AED 1 million of turnover, check whether you need to register for corporate tax at all.
- If you’re in a free zone, compare the relief with the Qualifying Free Zone Person regime before you decide.
- Forecast revenue for 2027 to 2029 and flag any year that might cross AED 3 million.
Our tax set-aside calculator helps you put money aside for the year you leave the relief, and the invoice generator keeps revenue records in one place so the AED 3 million test is easy to evidence. As of August 2026, the only change is the end date, but relief rules like this get reviewed, so check again before you file for 2029.
Sources
- UAE Ministry of Finance: Extension of small business relief until 31 December 2029
- Federal Tax Authority: Small business relief
- Federal Tax Authority: Corporate tax basis for natural persons
- UAE Ministry of Finance: Applicable taxable income threshold for corporate tax
- DLA Piper: UAE extends corporate tax relief for small businesses
This article is general information, not legal or tax advice. Laws differ between countries and states and change over time, so check the rules that apply to you or speak to a qualified professional.